

Revolut is looking to compete with American Express (Amex) by offering a rewards-based credit card product in the UK. The startup-focused news outlet Sifted reported:
Revolut is in the early stages of developing a points-based credit card, putting it in direct competition with incumbents such as American Express.
It’s the latest in a slew of new products developed by the UK fintech, which has over 50m customers globally and now offers everything from stocks and shares and crypto, to pet insurance.
Sometimes when I read news like this, my instinct as someone with experience in payments is to think: can Revolut really compete with Amex? Or is this part of a broader strategy? Amex has a strong position in the card rewards space, but I'm curious to understand the dynamics more and get into the next level of detail that news stories don't have space for. In this post, we'll go through:
Understanding interchange - the economics behind credit card rewards and why it varies by region
Amex’s regulatory advantage - how the Interchange Fee Regulation (IFR) gives Amex a unique position in the UK and EU
The card rewards calculation - how fintechs structure their reward programmes within regulatory constraints
How credit card strategy is evolving - from standalone premium products to integrated wider financial ecosystems
Understanding interchange
The main factor affecting credit card rewards is interchange. Credit card rewards are fuelled by interchange. It’s part of the fee that all businesses get charged when they allow users to pay with Visa or Mastercard credit or debit cards.
Different countries have different interchange rates for credit card transactions.
The higher the interchange fee, the better the rewards a cardholder gets, especially on credit card transactions. The US has one of the highest interchange fees in the world for credit cards, averaging 2.2% for consumer domestic credit transactions. In the US, consumers enjoy generous reward programmes. However, not everyone benefits, as the best rewards cards are unavailable to those with low credit scores.
The downside for businesses is that high interchange also means that companies pay more to accept card payments.
Interchange is actually one of three fees levied by the card acquirer - the entity that charges a business for processing a transaction. Examples of card acquirers in the UK, sometimes known as acquiring banks or simply “acquirers,” are Worldpay, Elavon, Adyen, and so on.
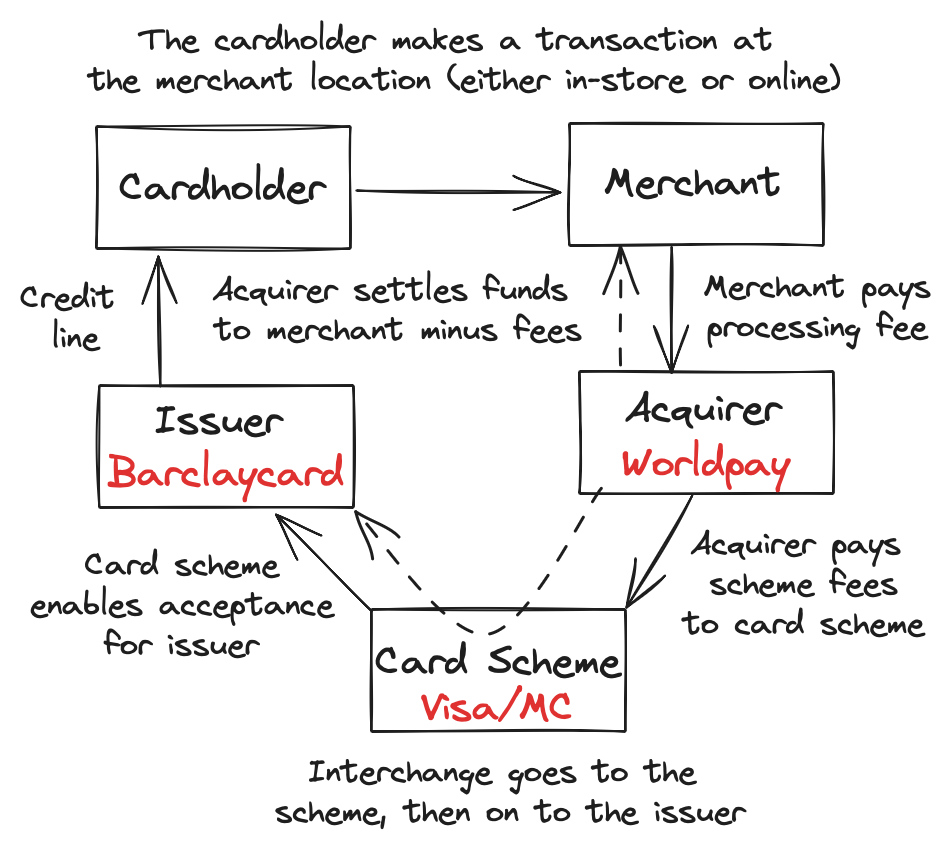
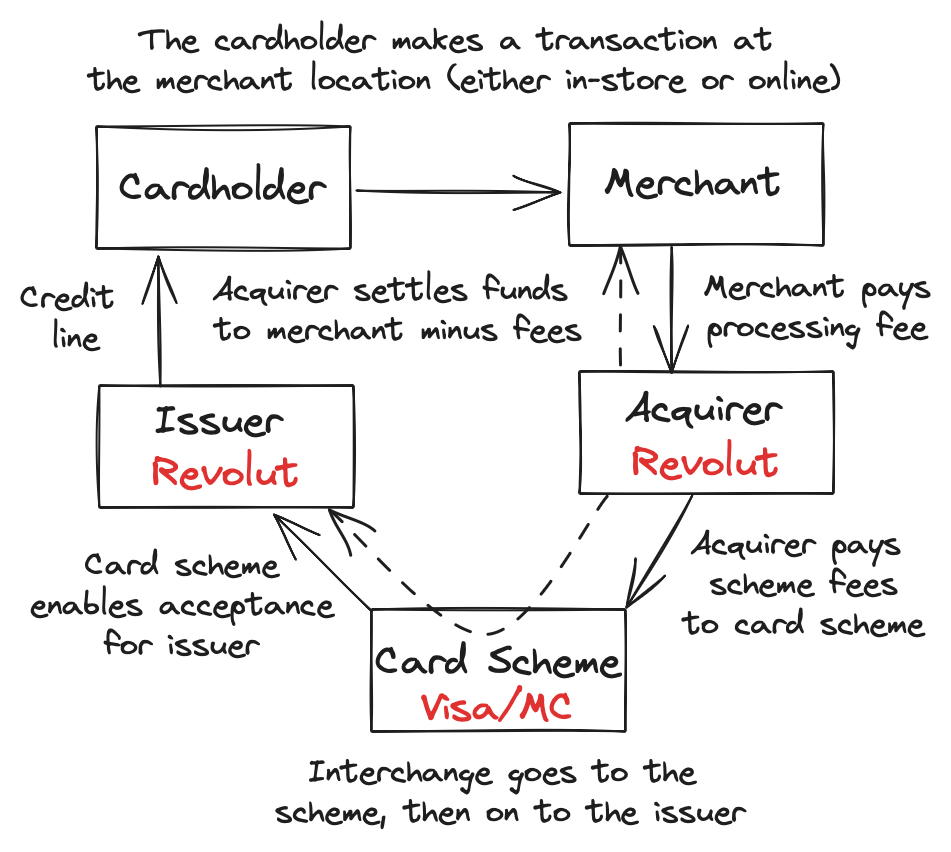
As part of the financial flow of a transaction, the interchange fee goes from the acquirer to the card network, e.g. Visa or Mastercard, and is then paid to the card issuer by the network. The card issuer is the one that provides a credit card to a consumer. Barclaycard, HSBC, and Santander are examples of card issuers in the UK.
In addition to the interchange fee, the acquirer also charges scheme fees (which are paid to Visa and Mastercard), and takes its own cut. Usually, the acquirer charges all three fees as a combined amount, but large retailers expect to see a breakdown of all three elements in a fully transparent pricing model.
The total fee retailers pay is sometimes called MSC, or Merchant Service Charge. The MSC is the sum of interchange plus scheme fees plus acquirer margin.
Revolut’s yet to be launched UK credit card will either be Visa or Mastercard branded (they currently offer debit cards badged with both Visa and Mastercard). When comparing any Visa or Mastercard credit card product with Amex, Amex holds an advantage that cannot be matched.
This is due to how credit card interchange is regulated in the UK and EU.
Amex’s advantage
The interchange rates for Visa and Mastercard consumer transactions are capped at 0.20% for debit cards and 0.30% for credit cards. This cap comes from the Interchange Fee Regulation (IFR).
The Interchange Fee Regulation (EU) 2015/751 was passed by the European Union in April 2015 and came into force on 9 December 2015. Since leaving the EU, the regulation has continued in force in the UK, as it was retained post-Brexit. A cap on interchange fees of 0.2% for debit cards and 0.3% for credit cards still applies to most consumer card transactions.
The hope was that the Interchange Fee Regulation (IFR) would lead to lower consumer prices as expressed in the regulation itself:
Regulating such fees would improve the functioning of the internal market and contribute to reducing transaction costs for consumers.
In reality, this is what happened:
Large retailers, many of which were on transparent cost-plus pricing models, saw their total cost of accepting payments reduce in line with the interchange fee reductions.
Small businesses did not immediately see a reduction in their processing costs, but over time, fees did reduce, mainly due to market competition.
Consumers suffered. Card issuers, now making less money per transaction, reduced the level of cashback and other card rewards they paid out.
The value of credit card rewards reduced in accordance with the reduction in interchange.
Before the IFR, interchange fees on credit cards were 0.8-1.6% (depending on the card type). When the 0.3% cap was instituted, the value of card rewards soon reduced by up to 80%.
Meanwhile, Amex was not affected by the interchange caps in the IFR.
Only so-called four-party credit card schemes were regulated.
In the UK, Amex is both an issuer and an acquirer. As well as Amex, the other two parties involved in transactions are the merchant and the cardholder, making Amex a three-party scheme. Three-party schemes were explicitly excluded from the IFR.
