

Welcome to Payments Culture!
This newsletter explores how money moves, around the world.
In this week’s edition I cover:
Ryanair’s move to save £3m+ in payments acceptance costs
The economics of Open Banking payments vs cards
Additional advantages of Pay by Bank
Consumer expectations and adoption challenges
The default effect in payment choice
My future outlook and recommendations
I hope you had a great summer! As we are now coming near to the end of September, the hot days of summer feel like a long time ago. In the UK we’re strapping in for more than six months of dreary rain and grey skies. The one advantage of living in a country with such sh*tty weather is that we have no excuse but to get our heads down and work hard for the next few months.
My August highlight was a late summer vacation. I’ll write more about my travels next week. But this post is about Pay by Bank and how it’s seeping into more and more online checkouts. What’s the significance of this? And could companies like Ryanair save £3m+ a year through Pay by Bank? Let’s get into the details.
Pay by Bank is powered by Open Banking technology. In the text below, I use both terms interchangeably to refer to the same bank account-based payment method.
Payments as cost control
Ryanair is Europe’s largest airline.1 They carried over 200m passengers last year (the first European airline to do so). The service is no-frills but always punctual and usually good value. If you want to fly to some locations in Europe, Ryanair may be your only option - their network is much bigger than legacy carriers such as British Airways and Lufthansa. In the early days, Ryanair’s business model was to fly to second-tier airports that traditional airlines often avoided, but over time, in many locations, they now compete directly with legacy carriers.2
Ryanair’s growth has been premised on exceptional and unwavering cost control.
This discipline extends across their entire business, including into payments. When I recently opened their checkout page I wasn’t surprised to see that they now offer Pay by Bank as their default payment method.
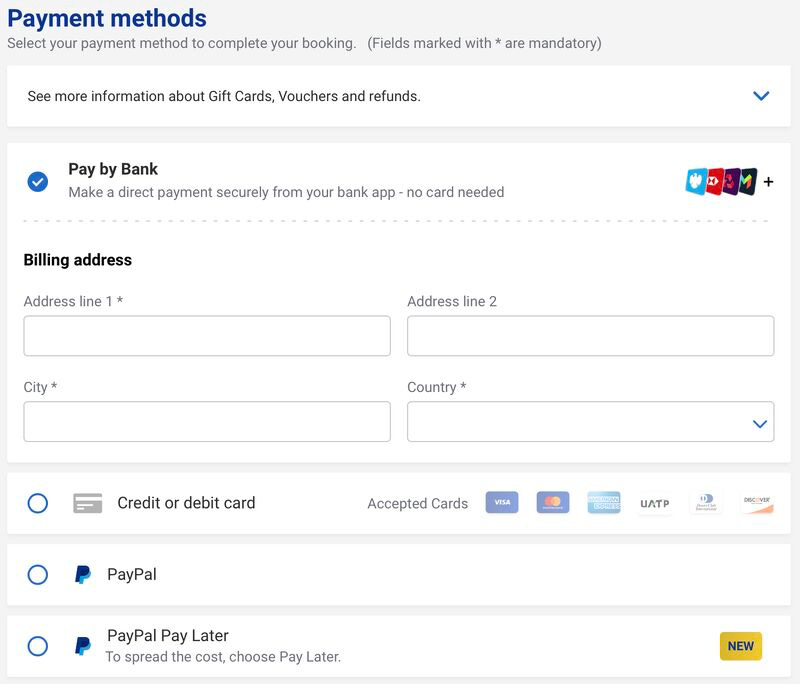
Pay by Bank is a term widely used for payments directly from a bank account (instead of from a credit or debit card). The main benefit to Ryanair is cost. For some businesses, it’s much cheaper to accept payments directly from a bank account than card payments. When transaction values are high — such as booking a ticket for several travellers in one payment — then the cost difference really shines through.
Let’s look at some of the economics:
The average payment transaction for Ryanair is around £803
Ryanair will pay merchant service fees to their card acquirer, PSP, or payment processor on every card transaction
The total fees paid will range from circa 0.45% for debit cards and 0.55% for credit cards4
On a £80 transaction this will equate to £0.36 (debit) and £0.44 (credit)
The cost base of card payments is fixed due to interchange and scheme fees that are paid to Visa and Mastercard and the issuing bank. But with Pay by Bank, the cost of payments are based on what the third party payment initiator – known as a PISP – sees as a fair price. True Layer, one of Europe’s largest Open Banking providers is the PISP for Ryanair, and while the exact pricing that Ryanair pays for Pay by Bank is confidential, usually Open Banking payments are priced as a per-item fee (pence per transaction) rather than as a percentage (ad valorem). In the case of a large airline like Ryanair a fee of around £0.20 per transaction would be possible.5 This equates to just 0.25% on a £80 average transaction.
Therefore, on average, with Pay by Bank, Ryanair would save £0.16 on every debit card transaction and £0.22 on every credit card transaction. A credit card transaction is likely to cost twice as much as a Pay by Bank transaction! And this is just the start.
Note: The above example assumes that these transactions are consumer domestic transactions. Card fees differ depending on the type of card used. I wrote more about the nuances of interchange fees in my recent post titled Can Revolut compete with American Express?
Business and commercial cards — unlike consumer cards — are unregulated and incur a fee of over 2%. If a business or a commercial card is used to pay at Ryanair, the total cost will be close to £2 per transaction, a world away from the possible 20p per transaction for an Open Banking payment.
Additionally, if Ryanair's merchant domicile for card payments is based in Ireland rather than the UK, due to a post-Brexit quirk, even consumer cards will attract fees of over 1%. Taken together these nuances mean that the potential cost savings highlighted above the minimum savings, and the average may be much higher.
It’s not just lower transaction fees
With Open Banking payments, businesses benefit from6:
Lower fees
Instant settlement
No chargebacks7
Lower fees are discussed above and will be covered further later in this post.
Looking at the other two points.
Instant settlement means that the merchant receives money from each payment instantly into their bank account. Businesses usually have to wait until the next day to receive funds, or in the case of some airlines, due to risk considerations, they have to wait days or even weeks.
Yet other than the lower fees, the most significant factor, and to be clear, the biggest positive of Open Banking payments for many merchants is lack of a chargeback mechanism.
The chargeback rate for the travel sector overall is often quoted as somewhere in the region of 0.5%-1% globally. This contains a large degree of variability depending on region and each specific merchant, but even a chargeback rate of 0.2% is highly disruptive and costly. This means that for every 1,000 transactions, two transactions are successfully disputed by a cardholder. For those two transactions, not only will an airline be debited for the original payment, but they'll also be hit with a £20 fee by their payment provider.8
Chargebacks drive up the total cost of payments, and it’s not surprising that many large merchants employ teams, and pay for tools, to specifically stop chargebacks from recurring. When chargebacks do occur, merchants usually try and win each case. The whole process is costly and time-consuming so for merchants, using Open Banking payments to say sayonara to chargebacks is a great!
Whether it’s lower fees, faster settlement, or no chargebacks, all of the benefits of Open Banking payments accrue to merchants and not to end users.
Last year I quoted a blog from Chris Skinner:
The thing is I always come back to: does anyone want Open Banking or Open Finance or Open Payments?
The industry does, yes, but the customer doesn’t.
Consumers are largely ambivalent.
They don’t benefit from lower fees.
They don’t benefit from faster settlements.
And consumers definitely lose out from the lack of a chargeback mechanism. Chargebacks are especially valuable in the travel sector. If an airline goes out of business before a customer takes their flight, then they can utilise the chargeback mechanism to get their money back.
It’s not Ryanair that we should worry about. From a financial perspective, Ryanair is one of the safest airlines in Europe. But if Pay by Bank proliferates there’s a risk that an airline insolvency of a smaller airline will lead to consumers not getting their money back.
In such a scenario the financial media will soon make clear that if a card had been used users would have been covered. In that event there’s reputational risk for Pay by Bank as a payment method. Even though companies who offer Pay by Bank — such as True Layer — will not make a financial loss in an airline insolvency scenario (as there’s no chargebacks), merchant-level risk should be part of the consideration when offering Pay by Bank as a payment option.
Consumer expectations
While the merchant-focused benefits are clear, consumer adoption of Pay by Bank remains a challenge — especially when card payments work so well in the UK.
